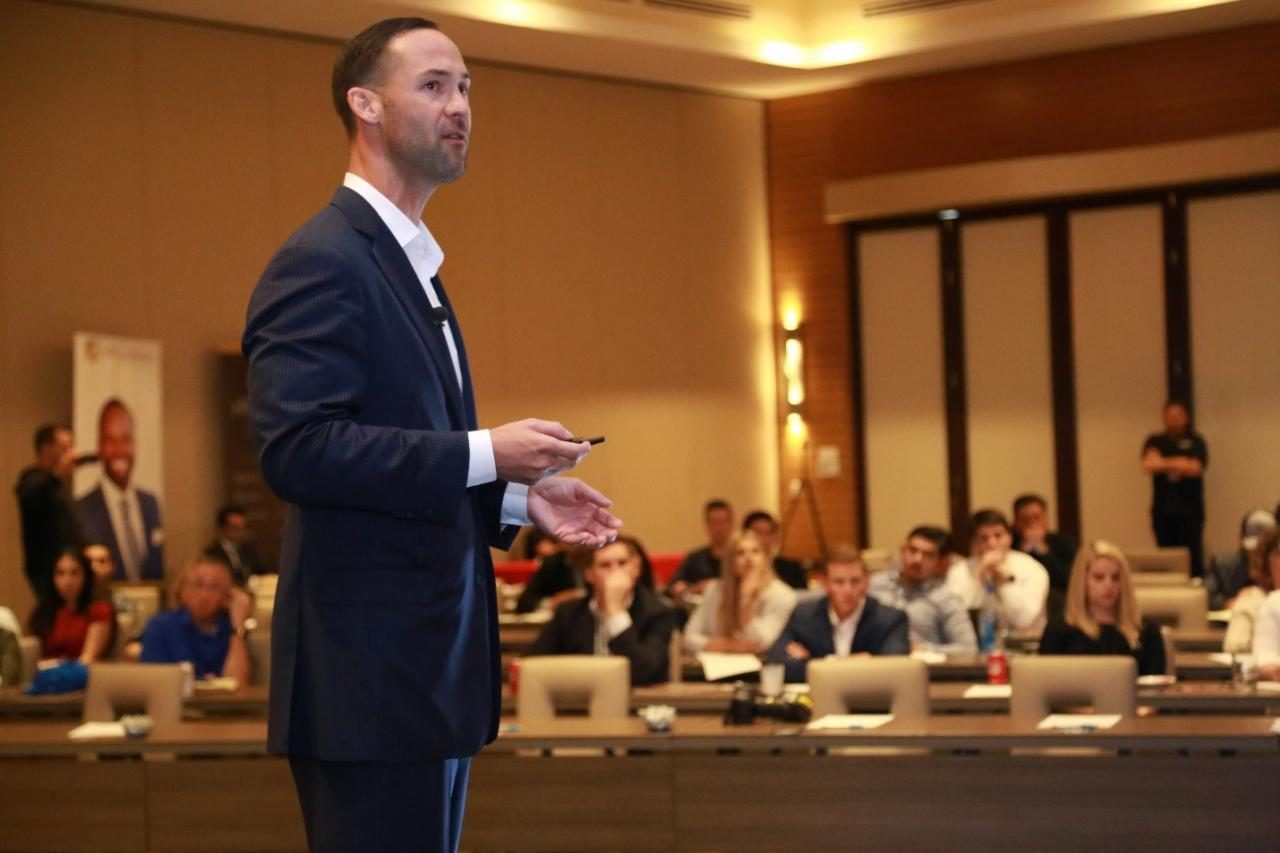
The High-Pressure World of Timeshare Presentations
Timeshare presentations are masterclasses in psychological persuasion. Often disguised as a brief, 90-minute informational session in exchange for free theme park tickets, a complimentary dinner, or a heavily discounted resort stay, these meetings frequently stretch into multi-hour marathons. Sales representatives are trained to bypass logical financial reasoning by leveraging emotional triggers. They use scarcity tactics ("this price is only valid if you sign today"), reciprocity (making you feel obligated to buy because they gave you free gifts), and social proof (applauding loudly when another family "joins the club" to create a false sense of urgency).
Before stepping into a sales presentation, it is vital to evaluate your long-term financial health and determine whether you can truly afford the ongoing commitment of maintenance fees, property taxes, and initial financing costs. To help you get an objective look at your financial situation before making major commitments, you can utilize free government tools. For instance, you can answer a 10-question financial well-being questionnaire developed by researchers to measure where you stand financially without having to perform complex math or gather account statements. Taking this step can provide a much-needed reality check before you agree to a long-term contract.
Sources: www.consumerfinance.gov
The Rescission Period: Your Critical (But Limited) Escape Hatch
If you have already signed a timeshare contract and are experiencing immediate buyer's remorse, your most powerful legal tool is the "rescission period," often referred to as a cooling-off period. This is a brief window of time during which a buyer can legally cancel a newly purchased timeshare contract for a full refund with no penalty. However, these rights are highly time-sensitive and vary dramatically depending on where the contract was signed. While most U.S. states have established statutory cooling-off periods—ranging from three business days to fifteen calendar days—some jurisdictions, such as North Dakota, do not have specific timeshare rescission statutes. In those cases, buyers must rely entirely on any voluntary cancellation clauses written directly into the developer's contract or consult a local attorney.
To execute a successful rescission, you must locate the specific cancellation clause in your contract, which is often buried in small print near the signature page. This clause will dictate the exact method of delivery required—typically a written letter sent via certified mail, return receipt requested, to a specific corporate address. Hand-delivered letters, emails, or phone calls are rarely accepted as valid proof of cancellation. Your written notice must clearly state your intent to cancel, the contract number, the date of purchase, and the names of all buyers. Because the clock starts ticking the moment you sign the contract, acting immediately and maintaining a paper trail with postal tracking is absolutely critical.
Sources: www.consumerfinance.gov
Points vs. Weeks: Demystifying Timeshare Formats
The timeshare industry has undergone a massive structural shift over the past few decades. Historically, timeshares were sold as "deeded weeks," where a buyer purchased a fractional interest in a specific physical condominium unit for a designated week of the year (e.g., Week 26 at a beachfront resort in Florida). This traditional format provided a tangible real estate asset that could, in theory, be willed to heirs. However, it lacked flexibility, locking owners into the same destination and calendar week year after year.
Today, the industry is dominated by "points-based" vacation clubs. Instead of buying a specific week, you purchase a block of points that act as a form of internal currency. These points can be redeemed to book stays across a network of resorts, choose different unit sizes, or travel during various seasons. While developers pitch this as ultimate flexibility, the reality is often far more restrictive. Popular resorts during peak travel seasons require an exorbitant number of points, and booking windows often open up to 12 or 13 months in advance. Owners who do not book the moment the window opens frequently find themselves unable to secure their desired vacation, leaving them with expiring points and ongoing financial obligations.
Sources: www.consumerfinance.gov
The True Cost of Ownership: Maintenance Fee Escalation
One of the most common traps for timeshare buyers is focusing solely on the initial purchase price or the monthly loan payment while ignoring the ongoing cost of maintenance fees. When you buy a timeshare, you agree to pay an annual maintenance fee to cover the upkeep of the resort, including landscaping, pool maintenance, utilities, and staff salaries. According to the American Resort Development Association (ARDA), the average annual timeshare maintenance fee has risen to $1,480 per weekly interval. These fees are not fixed; they rise almost every year, often outpacing the rate of inflation.
Furthermore, timeshare contracts typically contain clauses that allow the resort's homeowners association (HOA) to levy "special assessments." These are one-time, mandatory fees charged to owners to cover unexpected expenses, such as repairing major structural damage after a hurricane, replacing roofs, or undergoing massive resort-wide renovations. Because timeshare contracts are legally binding, perpetual agreements, you are obligated to pay these fees for as long as you own the timeshare. Failing to pay maintenance fees or special assessments can result in the debt being sent to collections, severe damage to your credit score, and eventual foreclosure.
Sources: www.arda.org
The Secondary Market Reality: Why Timeshares Have Zero Resale Value
During a sales presentation, representatives may imply that a timeshare is a valuable real estate investment that will appreciate over time or can be easily sold if you no longer want it. This is a dangerous misconception. In reality, timeshares have virtually zero resale value on the secondary market. The moment you sign the contract and walk out of the presentation, the value of your timeshare drops by 50% to 90%, much like driving a new car off the dealership lot.
This massive depreciation is driven by a severe supply-and-demand imbalance. There are hundreds of thousands of existing owners desperately trying to give away their timeshares just to escape the burden of annual maintenance fees. A quick search on secondary market platforms like eBay or RedWeek reveals thousands of active listings where owners are offering their timeshares for a single dollar, and in many cases, offering to pay the buyer's closing costs and first year of maintenance fees just to transfer the deed. Because timeshares are not appreciating assets and are highly illiquid, they should never be viewed as a financial investment.
Sources: www.ftc.gov
Legitimate Exit Strategies: Working with the Developer Directly
For owners who missed their rescission window and can no longer afford or use their timeshare, the safest and most reliable exit path is often working directly with the developer. Recognizing the growing public backlash against high-pressure sales and the rise of fraudulent exit companies, several major timeshare developers have established official, internal exit programs. These programs allow qualifying owners to surrender or "deed back" their timeshares directly to the company.
For example, Wyndham Destinations operates the "Certified Exit – backed by Wyndham" program, which is completely free of charge for eligible owners. In contrast, other developers like Marriott Vacations Worldwide offer case-by-case exit programs that may charge nominal administrative fees (typically around $400). To qualify for these official developer exit programs, you must generally meet strict criteria: your timeshare mortgage must be fully paid off, you must be completely current on all maintenance fees and property taxes, and you must submit a formal application. If you meet these requirements, contacting your developer's customer care or inventory management department directly is the most secure way to walk away.
Sources: clubwyndham.com
Recognizing Timeshare Resale and Exit Scams
Many timeshare buyers eventually face buyer's remorse and look for ways to exit their contracts. Unfortunately, this desperation has fueled a massive industry of fraudulent timeshare exit and resale companies. These scammers often promise to sell your timeshare quickly or legally cancel your contract in exchange for a hefty upfront fee, only to disappear once the payment is made.
To protect yourself, never pay upfront fees to an exit company that guarantees a sale. Deceptive and unfair business practices are illegal, and federal agencies actively work to prevent them. If you believe you have been targeted by a fraudulent timeshare exit scheme or a deceptive marketing company, you can report the fraud directly to federal consumer protection authorities to help investigators track down and stop these bad actors.
Sources: www.ftc.gov
How to Handle Timeshare Financing Disputes
If you financed your timeshare purchase through a retail consumer loan or a credit card, you may find yourself dealing with high interest rates and aggressive billing practices. When disputes arise regarding the terms of your loan, or if you believe you were misled by the lender's sales representatives, your first step should be to contact the financial institution directly to attempt a resolution.
If the company refuses to address your concerns, you have the right to escalate the issue. You can submit a formal complaint regarding troublesome financial products or services to federal regulators. The complaint will be forwarded to the financial company, which generally works to provide a response within 15 days.
General educational information only; it is not individualized financial, tax, lending, or investment advice. Verify current terms with an appropriate professional or official agency.
Sources: www.consumerfinance.gov
Special Timeshare Risks for Veterans and Military Families
Active-duty military members and veterans are frequent targets for timeshare developers, who often pitch exclusive "military discounts" or specialized financing. Sales representatives may try to make their loans sound as secure or official as government-backed programs. However, it is crucial to understand that timeshare financing is entirely private and carries none of the protections of official federal programs.
If you are a veteran looking for legitimate housing assistance, you should look into official VA-backed home loans and housing grants through the Department of Veterans Affairs rather than private vacation contracts. To verify your military service for legitimate veteran benefits, you or your next of kin can request free copies of your DD Form 214 (Report of Separation) online, via mail, or by fax through the National Archives, provided your discharge date was less than 62 years ago.
Sources: www.va.gov, www.archives.gov
Accessing Older Military Records for Legal Disputes
In some cases, older veterans or their heirs may need to retrieve historical military records to resolve legal disputes, plan estates, or verify eligibility for legacy benefits associated with old vacation properties. It is important to know that the rules and fees for obtaining these records change once a service member's separation date passes a specific historical threshold.
Military personnel records become archival and open to the general public 62 years after the service member separates from the military. Unlike newer records, which are generally free for veterans and next of kin, archival records are subject to a public fee schedule. A routine archival file of 5 pages or less requires a $25 flat fee, while files of 6 pages or more require a $70 flat fee.
General educational information only; laws, program rules, fees, and eligibility change. Confirm current requirements with the responsible government agency or a qualified professional.
Sources: www.archives.gov
Tax Realities and Debt Relief Options
Many timeshare buyers are falsely told that their maintenance fees or loan interest can be easily written off on their annual tax returns. In reality, the tax rules surrounding timeshares are highly strict, and misreporting these expenses can lead to audits or penalties. For instance, you cannot deduct maintenance fees or special assessments for a personal-use timeshare, and you can only deduct mortgage interest if the timeshare is a deeded property that qualifies as a first or second home under specific IRS guidelines. Furthermore, defaulting on timeshare debt can severely damage your credit score and lead to collections.
If timeshare debt has pushed you into a difficult financial position where you are struggling to pay your federal taxes, do not ignore the situation. You can use official online resources, such as the tax debt help tool provided by the IRS, to explore payment plans and installment agreements. Additionally, if a timeshare company or exit firm advises you to participate in a scheme that sounds like tax fraud, you can report the scam directly to federal tax authorities.
Sources: www.irs.gov
A Comprehensive Pre-Purchase Checklist
Before you attend any vacation ownership presentation or sign a binding contract, review this essential checklist to protect your financial interests:
1. **Calculate the True Cost:** Add the purchase price, interest on financing, and the annual maintenance fee (averaging $1,480 according to ARDA) over a 10-year period, factoring in a 5% to 8% annual fee increase.
2. **Check the Rescission Window:** Identify the exact number of days you have to cancel the contract under state law. Write down the physical address and specific mailing instructions required for cancellation.
3. **Research the Secondary Market:** Search platforms like eBay and RedWeek to see what existing owners are asking for the exact same points package or resort week. If hundreds of owners are listing it for $1, do not pay retail price.
4. **Assess Booking Availability:** Ask the sales representative to show you real-time booking availability for peak travel dates. If they refuse or make vague promises, assume booking will be highly competitive and restricted.
5. **Consult an Independent Professional:** Never sign a contract on the day of the presentation. Take the documents home and have them reviewed by a trusted real estate attorney or financial advisor who is not affiliated with the resort.
Sources: www.arda.org
- https://www.consumerfinance.gov/consumer-tools/
- https://www.ftc.gov/advice-guidance/consumers
- https://www.irs.gov/
- https://www.fcc.gov/consumers/guides/inmate-telephone-service
- https://www.archives.gov/veterans/military-service-records
- https://www.va.gov/
- https://www.consumerfinance.gov/consumer-tools/financial-well-being/
- https://www.arda.org/research-aif
- https://clubwyndham.com/shared/certified-exit.html
- https://www.archives.gov/veterans/military-service-records/ompf-archival-requests.html