The 50/30/20 split is a rule of thumb, not a rule. In high-rent areas the needs share is routinely larger, and forcing it to 50% is not a sign of failure. Customize the percentages to reflect your geographic and personal financial realities.
The Foundations of the 50/30/20 Budgeting Rule
Budgeting often carries a negative connotation, conjuring images of restrictive spreadsheets, tedious receipt tracking, and the complete elimination of personal pleasures. However, modern financial planning emphasizes sustainable systems over deprivation. One of the most enduring and practical frameworks for achieving this balance is the 50/30/20 budgeting rule. Rather than forcing you to track dozens of micro-categories—such as coffee, dry cleaning, and digital subscriptions separately—this method aggregates your monthly spending into three highly manageable macro-buckets: Needs, Wants, and Savings.
The Consumer Financial Protection Bureau (CFPB) highlights this approach as a flexible "spending rule to live by" rather than a rigid, punitive mandate. The primary objective is to reduce the cognitive load associated with money management. By categorizing your expenses into these three distinct pillars, you gain an immediate, high-level understanding of your cash flow. This structural clarity empowers you to make proactive financial decisions without feeling bogged down by administrative overhead. Whether you are trying to pay down high-interest debt, build an emergency fund, or simply stop wondering where your paycheck went each month, this framework provides a clear, actionable roadmap.
However, it is crucial to recognize that the 50/30/20 split is an aspirational guideline, not an absolute law. Personal finance is deeply personal, and economic realities vary widely based on geographic location, career stage, and family structure. The beauty of this system lies in its adaptability. By understanding the core principles of each category, you can customize the ratios to fit your unique financial landscape, ensuring that your budget remains a tool for empowerment rather than a source of stress.
Sources: www.consumerfinance.gov
Step 1: Calculating Your True Monthly Take-Home Income
Before you can allocate a single dollar to your needs, wants, or savings, you must establish an accurate baseline of your monthly net income. Many budgeting mistakes stem from using gross income (your salary before taxes and deductions) rather than your actual take-home pay. To build a functional budget, you must work exclusively with the money that actually lands in your bank account.
According to foundational budgeting guidelines from Consumer.gov, the first step in this process is gathering all relevant financial documents. This includes pay stubs, bank statements, tax documents, and records of any secondary income streams. For salaried employees with a consistent paycheck, identifying net income is straightforward: look at the final deposit amount on your pay stub after federal, state, and local taxes, Social Security, Medicare, and employer-sponsored health insurance premiums have been deducted.
If you have voluntary deductions taken directly from your paycheck—such as contributions to a traditional 401(k), a Health Savings Account (HSA), or a Flexible Spending Account (FSA)—you will need to decide how to account for them. Because these contributions represent active savings or essential healthcare coverage, many financial planners recommend adding them back to your net take-home pay for the purpose of the calculation, and then categorizing them under their respective buckets (Savings for 401(k) contributions, and Needs for health insurance or HSA funds). This ensures your percentages accurately reflect your total financial picture.
For freelancers, gig workers, or commission-based professionals, calculating monthly income requires a slightly different approach due to natural cash flow fluctuations. Consumer.gov recommends gathering your total income from the past 12 months, summing it up, and dividing by 12 to establish a reliable monthly average. During high-income months, it is wise to park the surplus in a separate holding account to cover the shortfall during leaner months, keeping your baseline budget stable and predictable.
Demystifying the "Needs" Category (50% Allocation)
The largest portion of your income under this framework—50%—is allocated to "Needs." These are the non-negotiable expenses that you must pay to maintain basic survival, keep your job, and protect your physical and financial well-being. If you were to lose your job tomorrow, these are the bills that you would absolutely have to pay to keep a roof over your head and food on your table.
Core components of the Needs category include:
* **Housing:** Rent or mortgage payments, property taxes, and home insurance.
* **Utilities:** Electricity, water, natural gas, trash collection, and basic internet (especially if you work from home).
* **Food:** Basic, nutritious groceries. This does not include dining out, ordering delivery, or purchasing specialty gourmet items.
* **Transportation:** Car payments, auto insurance, fuel, routine maintenance, or public transit passes required to commute to work.
* **Healthcare:** Health insurance premiums, prescription medications, and necessary co-pays.
* **Minimum Debt Payments:** The absolute minimum payments required on student loans, credit cards, auto loans, and personal loans. Failing to pay these minimums carries severe legal and credit consequences, making them essential obligations.
A common point of friction in modern budgeting is the rising cost of housing. In many high-cost-of-living (HCOL) metropolitan areas, rent alone can easily consume 40% to 50% of an individual's take-home pay. If your total needs exceed the 50% threshold, do not view this as a personal failure. It is a structural reality of your local economy. To balance the equation, you will need to make conscious trade-offs, typically by reducing your "Wants" allocation to ensure your "Savings" remain protected, or by exploring roommates, downsizing, or relocating to bring your structural costs back in line over the long term.
Sources: www.consumerfinance.gov
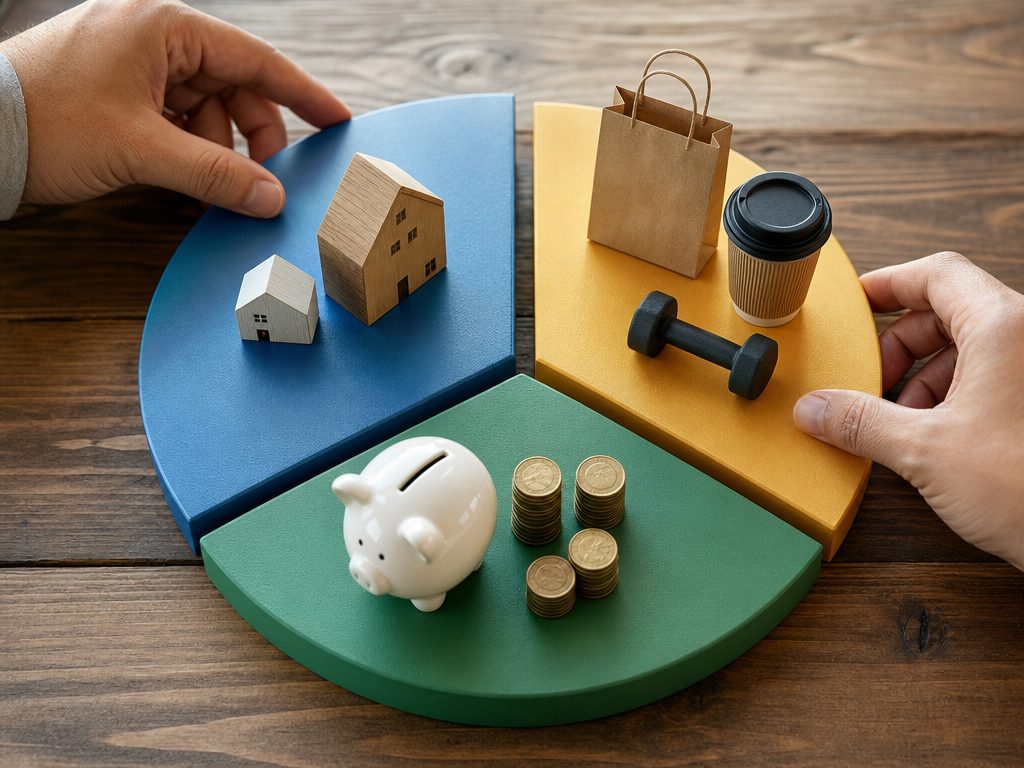
Navigating the "Wants" Category (30% Allocation)
The "Wants" category, comprising 30% of your net income, represents your lifestyle choices. These are expenses that enhance your quality of life but are not strictly necessary for survival or employment. While it can be tempting to view this category as frivolous, it is actually the engine that makes your budget sustainable over the long term. A budget that allows no room for enjoyment is highly prone to failure, much like an overly restrictive crash diet.
Typical expenses in the Wants category include:
* **Dining Out and Entertainment:** Restaurants, bars, concerts, sporting events, and movie tickets.
* **Travel and Leisure:** Vacations, weekend getaways, and recreational activities.
* **Subscriptions:** Streaming services (Netflix, Spotify, etc.), gym memberships, and subscription boxes.
* **Upgrades:** Buying a premium smartphone when your current one works fine, purchasing designer clothing, or upgrading to a luxury vehicle.
Distinguishing between a need and a want requires rigorous honesty. For example, clothing is a fundamental need, but buying a $200 designer jacket is a want. Similarly, reliable transportation is a need, but driving a brand-new SUV with a $700 monthly payment is a want.
The Wants category serves as your primary financial shock absorber. If you experience a sudden drop in income or an unexpected spike in essential expenses, the Wants category is the very first place you should cut back. Because these expenses are entirely discretionary, you can pause them instantly without damaging your credit score, risking eviction, or compromising your health. Regularly auditing your subscriptions and discretionary spending habits ensures that this category remains within its designated 30% boundary.
Prioritizing the "Savings" Category (20% Allocation)
The final 20% of your take-home pay is dedicated to "Savings." This category is your primary tool for building long-term wealth, securing your financial future, and protecting yourself against life's inevitable surprises. Rather than viewing savings as money you cannot spend, think of it as paying your future self first.
Under the 50/30/20 framework, the Savings category encompasses several distinct financial goals:
* **Emergency Fund:** Building a liquid cash reserve in a high-yield savings account. Financial experts generally recommend saving three to six months' worth of essential living expenses to cover unexpected medical bills, car repairs, or job losses.
* **Retirement Contributions:** Contributions to individual retirement accounts (IRAs), Roth IRAs, or employer-sponsored plans like a 401(k) (beyond any amount automatically deducted from your net pay calculation).
* **Extra Debt Paydown:** While minimum debt payments belong in the Needs category, any additional payments made to accelerate the payoff of high-interest debt (such as credit card balances or high-rate personal loans) are classified as Savings. Eliminating debt is a guaranteed return on investment because it frees up future cash flow.
* **Long-Term Goals:** Saving for a down payment on a home, a wedding, continuing education, or starting a business.
To ensure you consistently hit your 20% savings goal, automation is highly effective. Set up automatic transfers from your checking account to your savings or investment accounts to occur immediately after your paycheck is deposited. By removing the manual decision-making process, you eliminate the temptation to spend your savings on discretionary wants.
Sources: www.consumerfinance.gov
Customizing and Troubleshooting Your Budget Split
While the 50/30/20 split is an excellent benchmark, it is not a one-size-fits-all solution. Depending on your income level, debt load, and geographic location, you may need to adjust these ratios to create a realistic plan that you can actually stick to over time.
Consider these common scenarios and how to troubleshoot them:
* **The High-Rent Reality (e.g., 60/20/20 or 70/15/15):** If you live in an expensive city, your housing costs might push your Needs category to 60% or 70% of your income. In this situation, you must temporarily reduce your Wants category to keep your budget balanced. For example, a 60/20/20 split allows you to cover your high rent while still prioritizing a healthy 20% savings rate. If things are exceptionally tight, you may have to drop down to a 70/15/15 split, but your long-term goal should be to find ways to increase your income or lower your housing costs to restore your savings rate.
* **The Aggressive Debt Paydown Phase (e.g., 50/10/40):** If you are highly motivated to wipe out student loans or credit card debt, you can choose to aggressively shrink your Wants category to 10% and redirect the extra 30% toward your Savings/Debt Paydown bucket. This accelerated approach can shave years off your debt-free timeline.
* **The Low-Income Challenge:** For households earning close to the minimum wage, basic needs like rent, utilities, and groceries may consume 80% or 90% of total income. In these circumstances, saving 20% is mathematically impossible without assistance. The immediate focus should be on maximizing safety-net resources, seeking career development opportunities to increase earning potential, and saving whatever small amount is possible—even if it is just $10 a month—to build the habit of saving.
Regularly reviewing your budget is essential. At the end of each month, compare your actual spending against your target percentages. If you consistently overspend in one category, do not abandon the budget entirely. Instead, treat it as valuable data. Adjust your categories, refine your definitions of needs versus wants, and continue tweaking the system until you find a sustainable rhythm that aligns your daily spending with your long-term financial aspirations.